Accrual or cash method
The method switch changes the date an operation falls into: the accrual date or the payment date.
Find out what the business really earned: from gross to net profit and margins, on the accrual or the cash method.
The profit and loss statement (P&L) in Financist shows income, expenses and profit for a period: gross, operating and net, with margins. You can build it on the accrual or the cash method, group it by category or business direction, and decide which section each category belongs to. It suits managers who need profitability, not only the cash balance.
A profit and loss statement (P&L) shows how much the business earned in a period: expenses are subtracted from income to get profit. Unlike the cash flow statement, it does not answer "how much money came in" but "is the business profitable". The difference is explained in the guide to cash flow, profit and balance.
Gross and operating margins are calculated on direct income; net margin is calculated on all income of the period. The margin in the Total column is a ratio of sums, not a sum of percentages.
The method switch changes the date an operation falls into: the accrual date or the payment date.
Assign each category to direct, indirect, other, "auto" by operation type, or hide it. Users with the right to manage settings can change this.
Group profit by category or by business direction with a project breakdown; operations without a direction or project get their own row.
Gross, operating and net margin for each period and for the total, plus charts.
Period, accounts, legal entities, projects, directions, counterparties, tags; columns by day, week, month, quarter or year.
Jump from an amount to its transactions, download the report as CSV or print it.
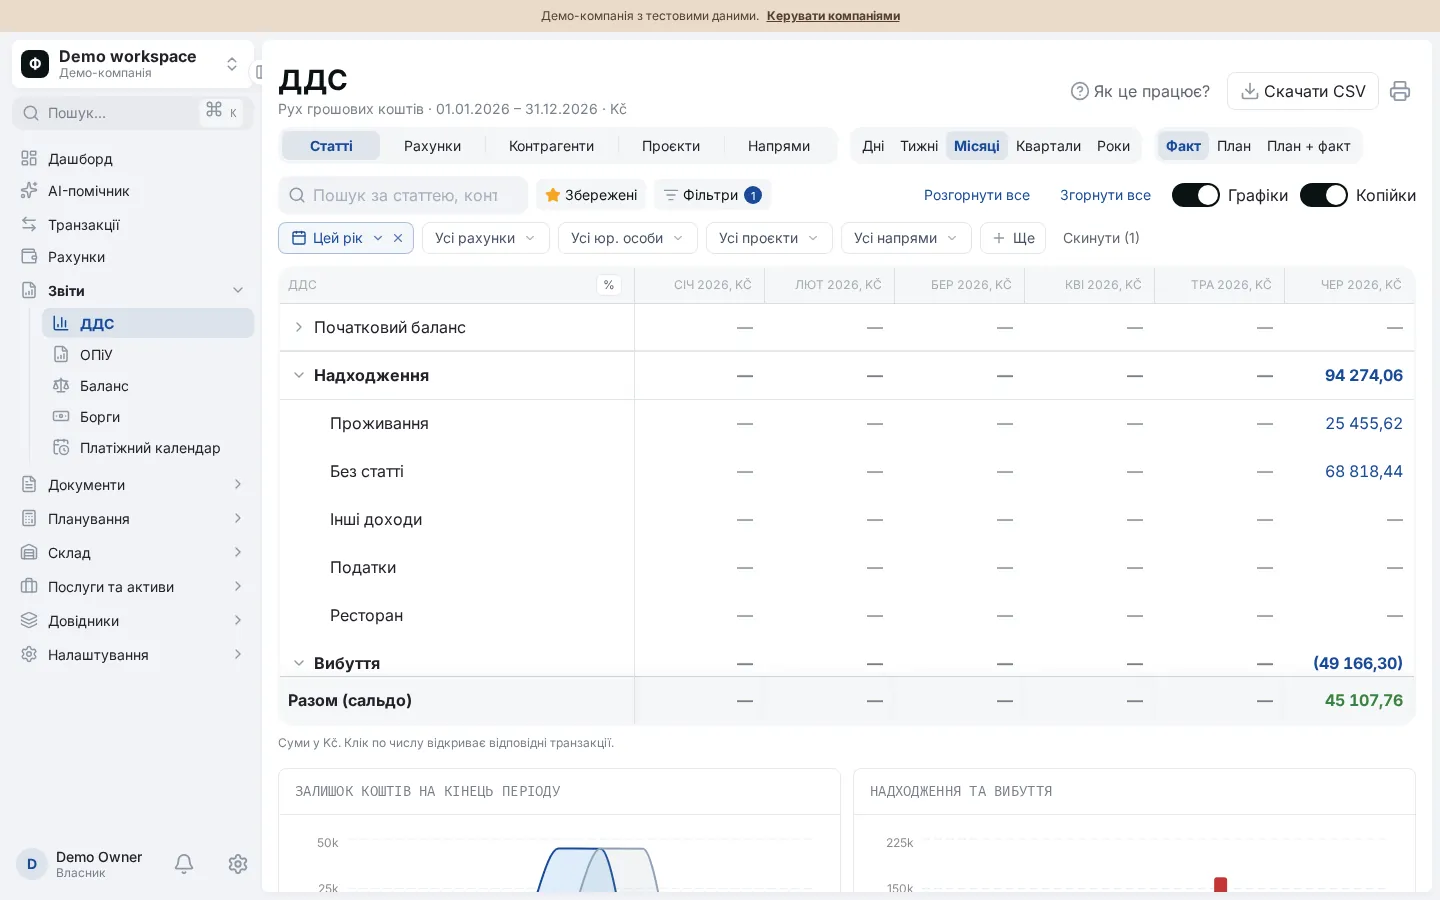
The same report can be built in two ways. Choose according to the question you are asking.
| Accrual | Cash | |
|---|---|---|
| When an operation counts | In the accrual month if one is set on the operation; otherwise on the payment date | On the day it is actually paid |
| Unpaid commitments | Counted immediately; the later payment is not counted twice | Not counted until paid |
| Answers the question | Was the business profitable in the period | How much profit we received in cash |
The P&L is for owners and finance managers who need to judge profitability rather than cash on hand: before changing prices, opening a new direction or talking to an investor. It answers questions such as:
For example, income is 20,000 EUR, direct expenses 12,000 EUR, indirect 5,000 EUR and other 500 EUR. Gross profit is 8,000 EUR (40% margin). Operating profit is 3,000 EUR (15%). Net profit is 2,500 EUR (12.5%). To compare with a plan, use budgets.
The cash flow statement shows money on the day it moves; the P&L shows profitability. Under the accrual method, income and expenses fall into the period they belong to, even if payment comes later. That is why a business can show a profit in the P&L and still be short of cash in the cash flow statement.
The accrual method shows the real profitability of a period because it counts commitments immediately. The cash method is simpler: it takes only paid operations by payment date. Accrual is usually used for management decisions, and the cash method for reconciling with actual cash movements.
Direct expenses relate to producing the goods or delivering the service and form gross profit. Indirect ones, such as rent or administration, reduce it to operating profit. You can change each category section in the P&L settings or leave it on "auto", in which case the operation type decides.
No. The P&L shows actuals only. The plan/actual switch is in the cash flow report, and a plan of income and expenses by category with its execution is kept in budgets.
The list of transactions that make up the amount, with the same period and filters. In accrual mode the transactions are selected by payment date, so the list can differ from the number in the cell.